Now Playing
Bri
0:00
0:00
Auto-advance
David Abreu has spent the last twenty years helping retirees and pre-retirees protect what they have built — with income strategies, tax-aware planning, and independent guidance drawn from across the marketplace.
Forbes Finance Council Member · Author · The Retirement Rescue SystemLicensed nationwide — David compares highly rated companies across the marketplace so the strategy is built around you, not one carrier.
How do you turn a lifetime of savings into a retirement built for protection, income, and long-term confidence?
For the last twenty years, David Abreu has helped retirees and pre-retirees turn a lifetime of savings into a retirement built for protection, income, and long-term confidence.
As Founder and CEO of Pacific United Financial Group, David runs an independent, nationwide practice. He works across the marketplace — not for any single carrier — so the plan is built around the client.
His work has been featured through the Forbes Finance Council, and he is the author of The Retirement Rescue System — a practical guide to protecting retirement savings, generating income, and planning with clarity.
How the practice thinks about retirement risk, income, and the questions worth asking early.
A written process that treats retirement as its own planning problem — with different math, different risks, and a different measure of success than the accumulation years.
Step One
An unhurried review of every account, income source, and obligation — on paper, before anything is recommended.
Step Two
A written strategy for income, protection, and taxes — with highly rated carriers evaluated side by side.
Step Three
Every transfer, rollover, and application handled in your presence with a written checklist and timeline.
Step Four
Ongoing monitoring of markets, tax law, and carrier ratings — with scenarios re-run whenever the terrain shifts.
Step Five
Written amendments whenever your circumstances, health, family, or goals change — measured against the original strategy.
Select any name from the roster to listen. The player advances automatically.
Every recording above is from a real Pacific United Financial Group client. Names are shown as provided.
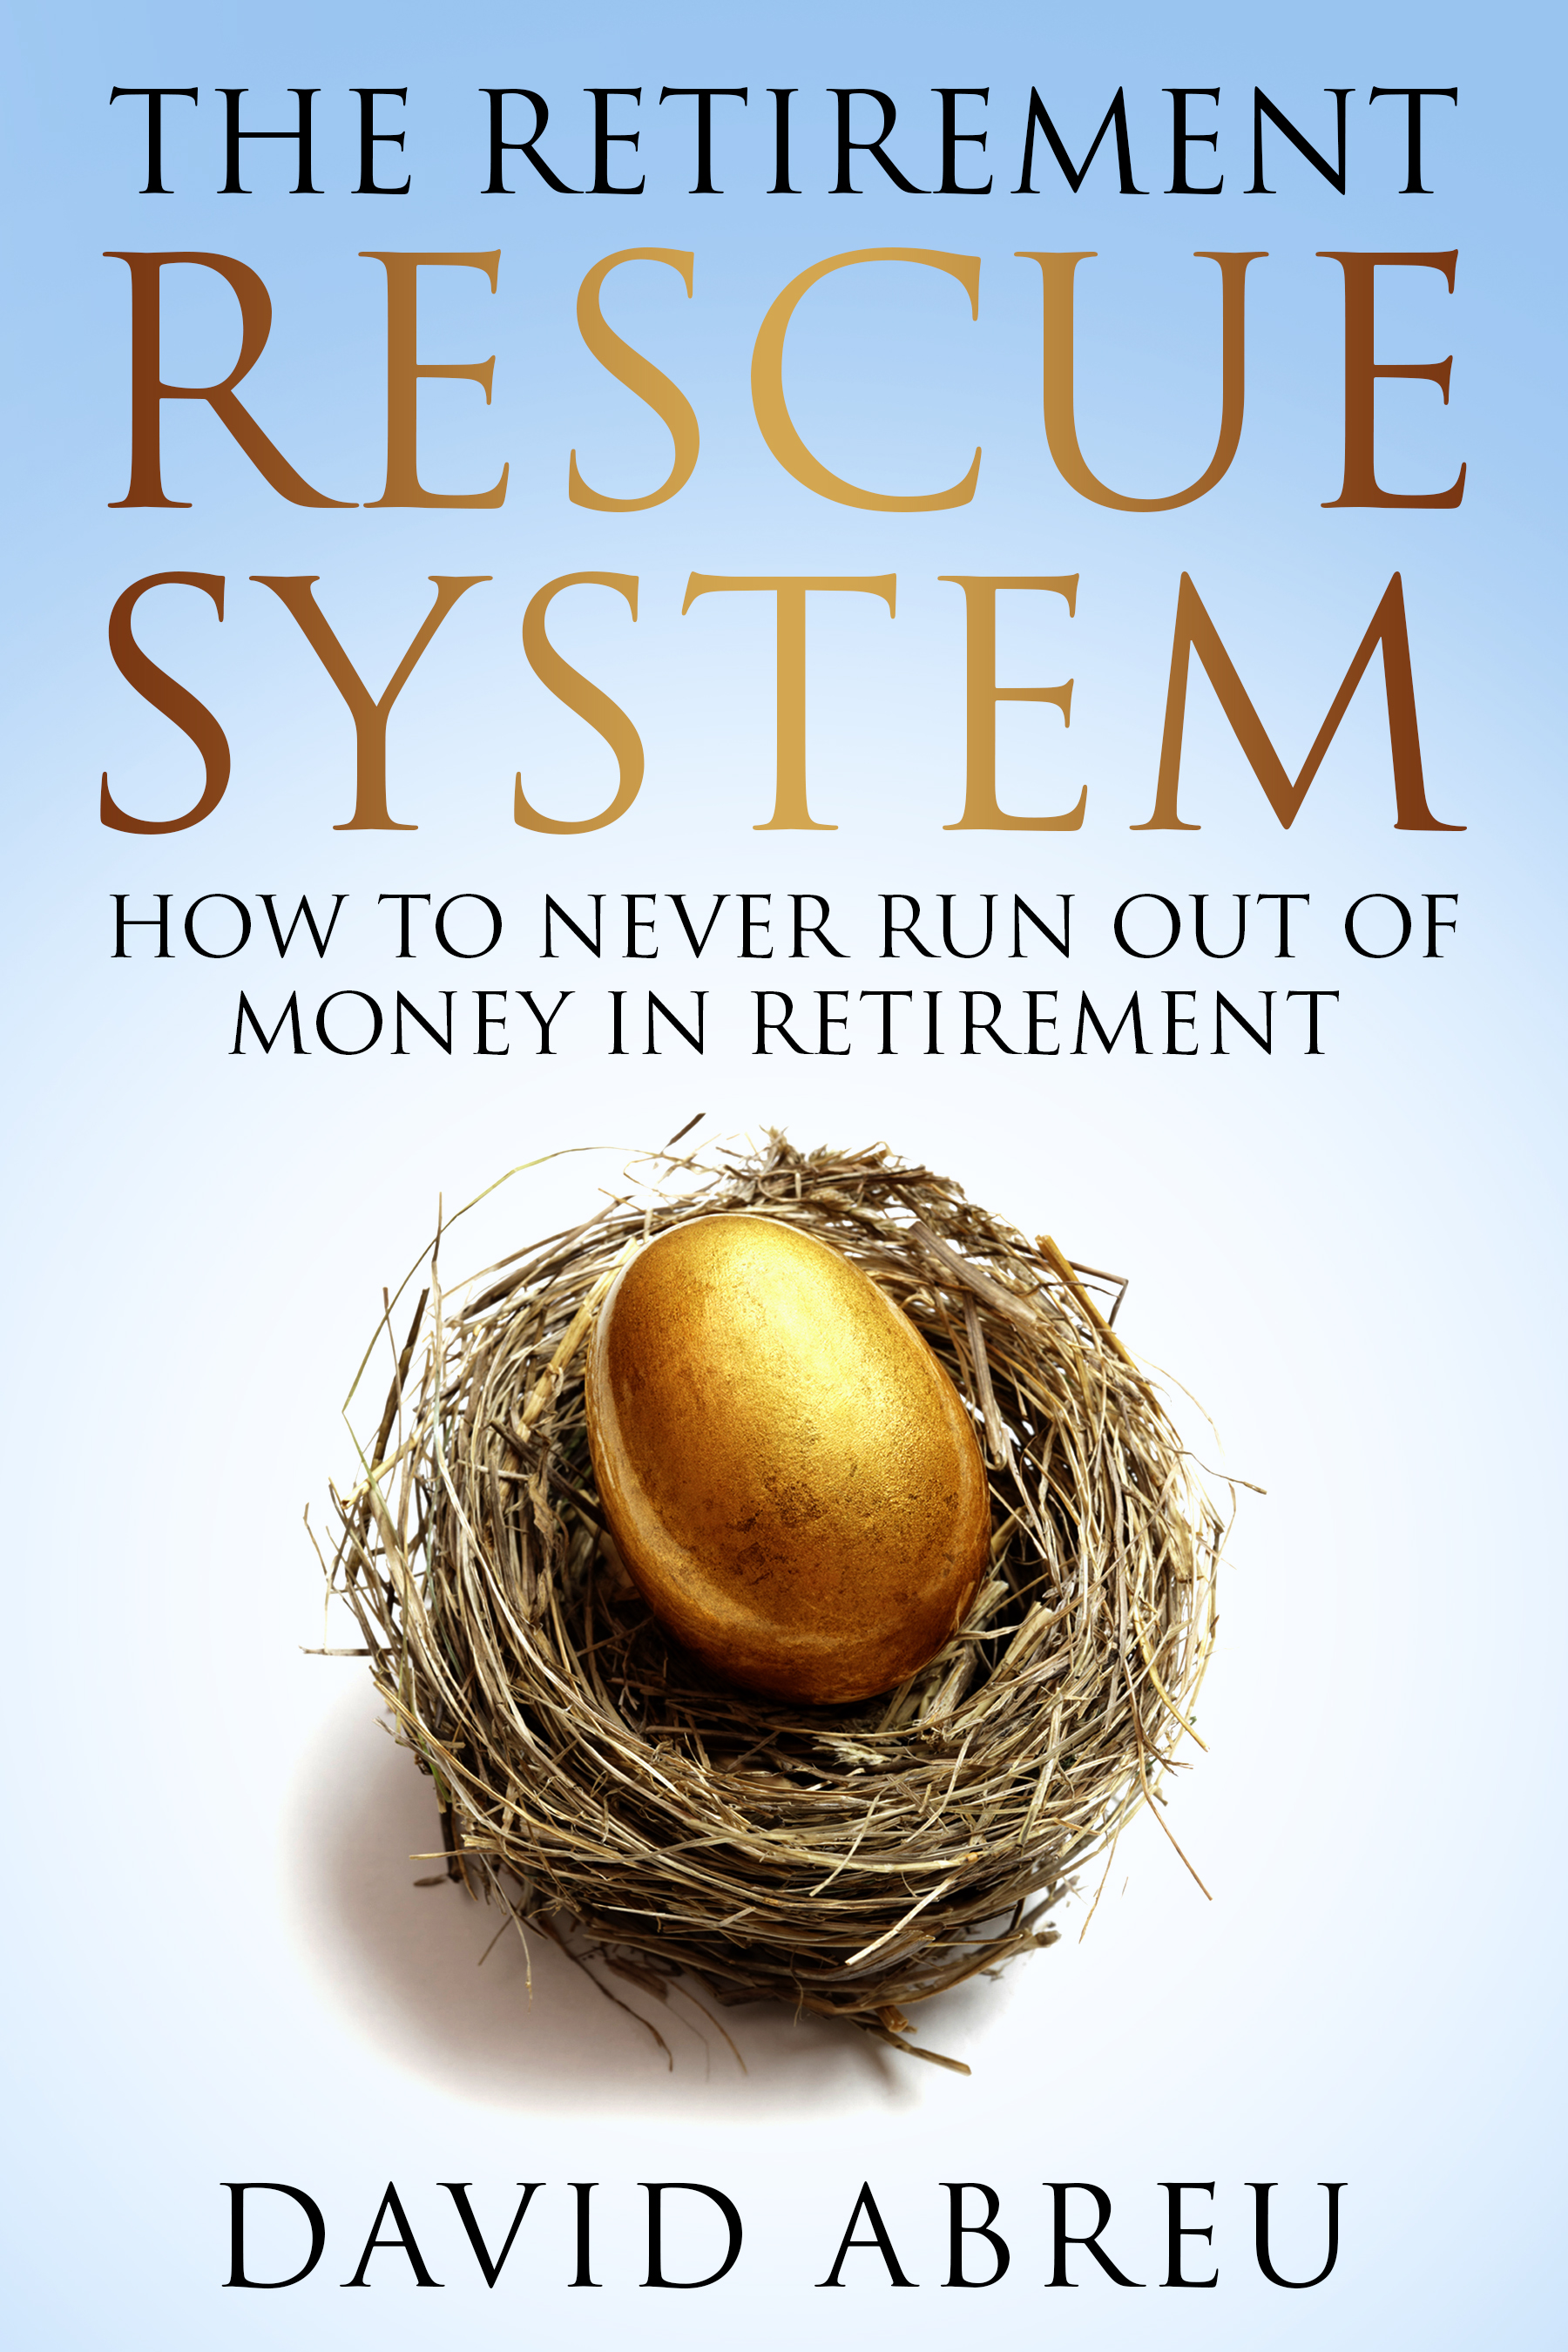
How to Never Run Out of Money in Retirement.
Written for Americans within a decade of retirement, the book distills two decades of client conversations into a plain-spoken framework — the same one used inside Pacific United Financial Group.
You will learn how to identify the risks most portfolios miss, why the accumulation playbook stops working the day distributions begin, and how to think about income, taxes, and legacy as one connected question.
It is a short read by design. The intention is to leave you with a better set of questions to bring to any advisor — including David himself.
Pacific United Financial Group is not a fit for everyone — and we would rather say so up front than waste your afternoon.
If this isn't a fit, we'll happily point you toward someone better suited.
If you are drawing income from an invested portfolio, it applies. Early-retirement losses compound against a withdrawal plan — the same average return, front-loaded with losses, can drain the account a decade sooner.
Strong past performance doesn’t guarantee future results. As you near or enter retirement, the goal shifts from growing your money to protecting it, reducing taxes, and creating income that lasts. A new strategy now can help you keep more, pay less in taxes, and create guaranteed income you can’t outlive.
The right filing age depends on health, marital status, other income, tax bracket, and whose benefit is larger. We model your specific case in writing before recommending an election age.
One of the most under-planned windows in American retirement. Healthcare costs and income sequencing must be handled together — a small change in reported income can move a household across an ACA subsidy cliff.
In your interest, in writing, with the reasoning shown. Not every advisor using the word operates that way. Ask for the specific language of the standard they follow — and ask them to sign it.
Thirty minutes. No paperwork. No product presentation. David asks about your accounts, timeline, and what a good retirement looks like to you. If there's nothing to help with, he says so. If there is, he explains the next step in writing.
Most clients have $250,000 or more in investable retirement assets. Below that, we'll say so on the first call and point you toward a professional who's a better fit for your stage.
The difference is not the products — it's the sequence. Most portfolios are built for accumulation and repurposed for retirement. Our process treats retirement as its own planning problem: different math, different risks, different measure of success.